
Most homeowners assume mold is covered the moment they find it. It isn’t that simple. A solid mold remediation insurance coverage checklist is what separates a paid claim from a denied one. Insurance companies treat mold as a byproduct of something else, not a standalone event, and if you can’t prove the right chain of events, they don’t pay. This guide walks you through what actually triggers coverage, what to document, how limits work, and exactly what to do from the moment you spot mold to the day your claim closes.
Table of Contents
- Key Takeaways
- 1. What actually triggers mold remediation coverage
- 2. What your policy limits actually look like
- 3. Critical documentation for a mold insurance claim
- 4. Step-by-step mold remediation insurance coverage checklist
- 5. Coverage comparison by common loss scenarios
- My honest take on where homeowners go wrong
- How Themoldgenius helps homeowners through remediation and claims
- FAQ
Key Takeaways
| Point | Details |
|---|---|
| Mold coverage is never standalone | Coverage only applies when mold results from a specific covered peril like a burst pipe or storm intrusion. |
| Documentation wins claims | Photographs, moisture readings, project logs, and contractor scopes are what adjusters actually review. |
| Sub-limits are often low | Standard mold sub-limits run $1,000 to $10,000, but endorsements can expand this significantly. |
| Independent hygienists matter | Using a separate company for testing and remediation prevents conflicts of interest that kill claims. |
| Deadlines cost homeowners money | Missing the 180-day debris removal reporting deadline is one of the most common and expensive mistakes. |
1. What actually triggers mold remediation coverage
Before anything else, you need to understand what makes a mold claim valid. Mold coverage is derivative of a covered water or fire peril. Your policy doesn’t have a mold line item. It has a water damage section, and mold coverage rides along when the water source qualifies.
The key concept adjusters use is “proximate cause.” That means the direct, covered event that set off the chain leading to mold. A burst pipe in January qualifies. A slow roof leak that went unnoticed for two years does not. Chronic moisture or maintenance issues are the most common reason mold claims get denied outright.
Covered events typically include:
- Burst or frozen pipes
- Storm-driven water intrusion through a roof or window
- Fire suppression water (from sprinklers or firefighting)
- Accidental discharge from appliances like a dishwasher or washing machine
- Overflow from a plumbing fixture
What policies consistently exclude are flooding (unless you carry separate flood insurance), groundwater seepage, humidity, condensation, and any damage attributed to a lack of maintenance. Many policies also carry sublimits specifically for mold, meaning even a valid claim may be capped well below your home’s actual remediation cost.
Pro Tip: Read your policy’s mold-related exclusions before you file, not after. Look for the words “fungi,” “mold,” and “wet rot” in the exclusion section. Some policies exclude all three separately.
2. What your policy limits actually look like
Here’s where most homeowners get blindsided. Your dwelling coverage might be $400,000, but mold may be capped at a fraction of that. Standard mold sub-limits typically range from $1,000 to $10,000 per claim, which often doesn’t cover full professional remediation in a finished basement or attic.
The comparison below gives you a realistic picture of what different coverage types look like:
| Coverage type | Typical limit | Notes |
|---|---|---|
| Basic mold sub-limit | $1,000 to $10,000 | Built into standard HO-3 policies; often insufficient |
| Optional mold endorsement | Up to $50,000 to $100,000 | Available from most major carriers for added premium |
| Debris removal | 5% of dwelling coverage | Strict 180-day reporting deadline applies |
| Additional living expenses (ALE) | 20 to 30% of dwelling coverage | Covers hotel and meals if home is uninhabitable |
| Ordinance or law coverage | Varies by policy | May cover code-upgrade costs during remediation |
Optional mold endorsements typically cost $50 to $100 per year and can push your coverage ceiling to $50,000 or higher. If you’ve had water issues in the past, or you live in a humid climate, that added premium is worth a serious conversation with your agent.
A few things to watch for beyond the main sub-limit:
- Whether your policy covers contents damaged by mold separately from the structure
- Whether ALE kicks in if mold makes part of the home temporarily unusable
- Whether debris removal is listed as a separate coverage or folded into the dwelling limit
Coverage varies more than most homeowners realize, both by state and by carrier. Always request a written coverage summary from your insurer before you need it.
3. Critical documentation for a mold insurance claim
This is where claims are won or lost. You can have a completely valid mold damage insurance claim and still walk away with nothing if your documentation doesn’t hold up. Here’s what to gather and maintain from the moment you find mold:
-
Discovery log. Write down the exact date and time you found mold, what you observed, where it was located, and what the suspected moisture source was. This becomes your claim’s foundation.
-
Photographs and video. Shoot wide angles and close-ups. Include a ruler or common object in the frame to show scale. Capture moisture meter readings on camera if you have one. Timestamp everything.
-
Moisture source documentation. If a pipe burst or an appliance leaked, photograph the source of water before any repairs. Get the plumber’s invoice or repair report showing what failed and when.
-
Independent mold inspection report. Hire a certified industrial hygienist (CIH) before remediation begins. This pre-remediation report establishes the baseline. Insurance adjusters routinely require this to avoid conflict-of-interest issues when the same company does both testing and cleanup.
-
Remediation contractor’s scope of work. The written scope should reference industry standards, specifically IICRC S520 and EPA guidelines. Industry standards directly influence what costs an insurer will accept as reasonable and necessary.
-
Daily project log during remediation. Track dates, work performed, materials used, and who was on site. This protects you if the insurer questions the timeline or scope.
-
All invoices and receipts. Organize these by category: remediation labor, equipment rental, debris disposal, contents pack-out, and temporary housing if applicable.
-
Post-remediation clearance report. This is non-negotiable. Clearance testing by a third-party hygienist is what most insurers require before finalizing payment. Budget for it and schedule it as part of your remediation plan, not as an afterthought.
Pro Tip: Never use the same company for both mold testing and mold removal. Adjusters view this as a conflict of interest, and it can give them grounds to dispute or reduce your payout.
4. Step-by-step mold remediation insurance coverage checklist
Use this checklist as your working reference from discovery through claim closure:
- Stop the moisture source immediately. Turn off water, patch the roof, or call a plumber. If the moisture is ongoing, your insurer can argue you failed to mitigate, which reduces what they owe.
- Notify your insurer within 24 to 48 hours. Most policies require prompt reporting. Send an email or follow up any phone call in writing so you have a timestamped record.
- Do not begin remediation before the adjuster inspects. Ask your insurer how soon they can send an adjuster. Major cleanup before the adjuster sees the damage can create disputes about scope.
- Hire an independent hygienist for the pre-remediation assessment. Get the inspection report in writing before any work begins.
- Gather all documentation listed in section 3. Photographs, moisture source records, contractor scope, and a project log.
- Track all deadlines. Debris removal reporting deadlines are typically 180 days from the date of loss. Missing this deadline can cost you thousands in coverage.
- Submit a complete claim package. Include the adjuster’s assignment number, all photos, the hygienist’s pre-remediation report, the contractor’s scope and invoices, and any ALE receipts.
- Follow up in writing every 10 to 14 days. If you haven’t heard back, send an email. Paper trails matter in disputes.
- Schedule clearance testing once remediation is complete. Submit the clearance report to your insurer to finalize payment.
- If your claim is denied or underpaid, appeal. Underpayment disputes over scope and pricing are common. A strong documentation file supports a formal appraisal or appeal.
Pro Tip: If your claim is denied and you believe the coverage should apply, ask your insurer for a written denial with the specific policy language they’re relying on. That letter is what a public adjuster or attorney will need to help you fight back.
5. Coverage comparison by common loss scenarios
Not all mold situations sit in the same coverage category. Where your mold comes from changes what your policy will and won’t pay.
A burst pipe in a finished basement is the clearest covered scenario. The event is sudden, accidental, and documented by a plumber. Mold that develops within days of that event has a strong causal chain. Compare that to a bathroom with mold on the ceiling from years of poor ventilation. That’s a maintenance issue, and no policy language covers it.
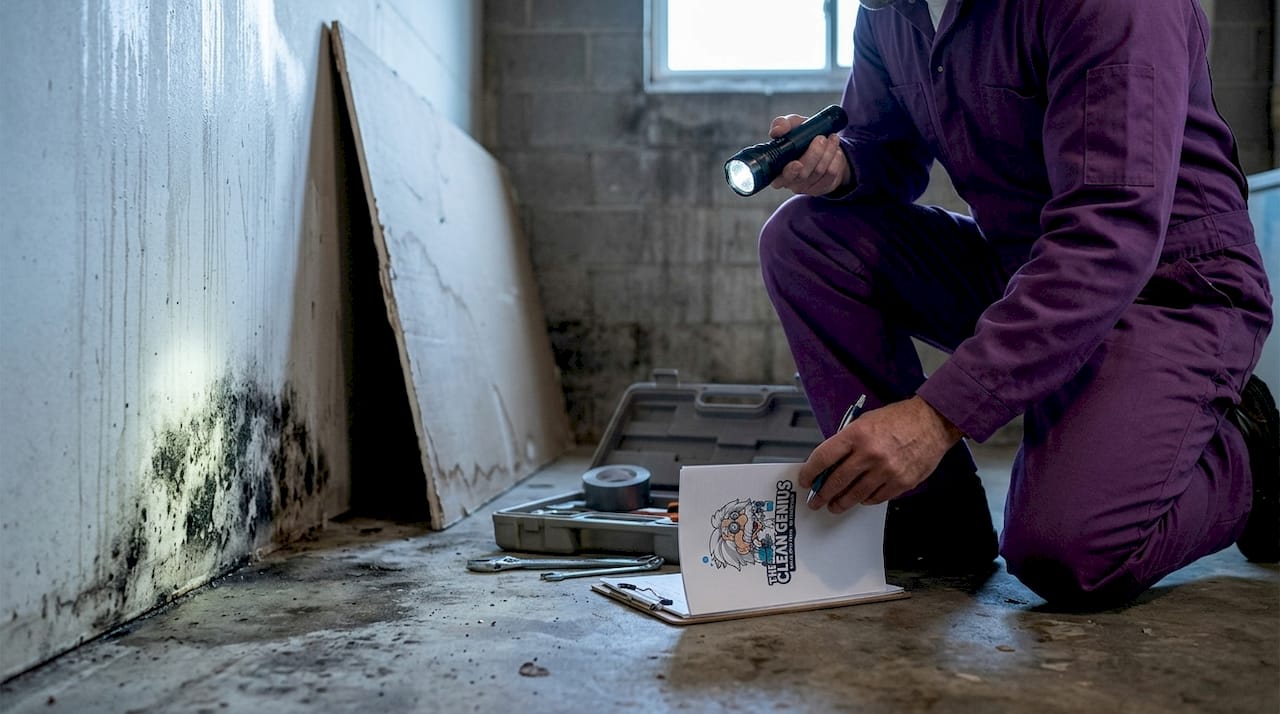
Storm-related water intrusion falls in the middle. If water entered through a damaged roof during a named storm and you can prove it, the claim is often valid. But if the roof had existing damage and the storm just accelerated it, adjusters may attribute the cause to deferred maintenance rather than the storm itself.
Flood-related mold is excluded under standard homeowners policies. You need a separate National Flood Insurance Program (NFIP) policy or private flood policy for that. Homeowners in flood-prone areas who skip this coverage often discover the gap only when it’s too late.
The mold coverage that flows from fire suppression water is one of the least-known valid scenarios. If firefighters used water or foam to extinguish a fire and mold developed in the following weeks, that mold is typically covered under the fire portion of your policy. Document it the same way you would any other claim.
My honest take on where homeowners go wrong
I’ve seen clean-cut mold claims turn into six-month fights, and I’ve seen complicated situations resolve quickly. The difference almost always comes down to two things: documentation and who the homeowner called first.
Most people call a remediation company the day they find mold. That’s understandable. But when that company starts tearing out drywall before the adjuster has visited or before an independent hygienist has assessed the situation, the claim gets complicated fast. Adjusters don’t like reconstructing what happened. They want to see it.
The other pattern I keep seeing is homeowners who have valid claims but don’t know their sub-limits. They assume the policy will cover the full bill, then find out mid-project that their mold cap is $5,000 and they’re already past it. Knowing your limits before you need them lets you make better decisions about endorsements or out-of-pocket contingency funds.
My biggest piece of advice: get the independent hygienist in before any work starts. That single step separates homeowners who get paid from those who spend months arguing. And if your claim gets denied despite solid documentation, a public adjuster can often recover money that most homeowners walk away from.
— Jim
How Themoldgenius helps homeowners through remediation and claims
When you’re dealing with mold, you need a company that understands both the remediation process and how insurance actually works. Themoldgenius works directly with carriers including Allstate, State Farm, USAA, Farmers, and Liberty Mutual, and they know what documentation adjusters expect.
Their Pure Cloud Technology uses a dry fogging system to treat mold in places traditional methods can’t reach, behind walls, above insulation, in tight corners, without tearing your home apart. Most jobs finish in a single day. Their process covers diagnosis with thermal imaging, removal with the Pure Cloud system, and prevention to address the root cause. Whether you’re dealing with basement mold, an attic problem, crawlspace growth, or water damage, Themoldgenius provides the documentation and clearance support your claim needs. Get a free estimate today at themoldgenius.com.
FAQ
Does homeowners insurance cover all mold removal?
No. Homeowners insurance only covers mold removal when the mold results from a covered peril, such as a burst pipe or storm water intrusion. Mold caused by gradual seepage, humidity, or poor maintenance is typically excluded.
What mold coverage limits should I expect?
Standard mold sub-limits range from $1,000 to $10,000, which often falls short of actual remediation costs. Optional endorsements can raise coverage to $50,000 or more for a relatively small annual premium.
Do I need an independent hygienist for my claim?
Yes. Most insurers require a pre-remediation assessment and a post-remediation clearance report from a certified industrial hygienist who is separate from the remediation contractor. Using the same company for both creates a conflict of interest that can get your claim reduced or denied.
What is the debris removal reporting deadline?
Most policies require you to report debris removal within 180 days of the date of loss. Missing this deadline can result in losing coverage for a significant portion of your remediation costs.
Can a denied mold claim be appealed?
Yes. If your claim is denied, request the written denial with specific policy language cited. You can file a formal appeal with your insurer or hire a public adjuster to review your documentation and negotiate on your behalf.